Summary
Paying for senior living without selling your house is possible when you strategically use multiple income sources and compare your complete budget. Explore how rental income, retirement funds, home equity options, and community cost savings can work together to support your move.
- Treat your house as a financial asset by calculating net rental income after accounting for property management fees, taxes, insurance, repairs, and vacancies
- Compare your full homeownership costs (mortgage, utilities, property taxes, insurance, maintenance) against community fees that replace services like meals, housekeeping, utilities, and transportation
- Combine multiple funding sources such as Social Security, pensions, retirement account withdrawals, investment income, and savings to create a sustainable monthly budget
- Consider home equity loans, home equity lines of credit, or reverse mortgages to access equity without an immediate sale, but review each option carefully with financial and legal professionals
- Choose a community like Whispering Oaks that offers flexibility, allowing you to adjust services and financing decisions over time rather than committing to one permanent choice at move-in
Paying for senior living without selling your house may feel complicated, but a sale is not always required. With a realistic budget and the right mix of income sources, you may be able to keep a familiar property while moving to a community that simplifies everyday routines.
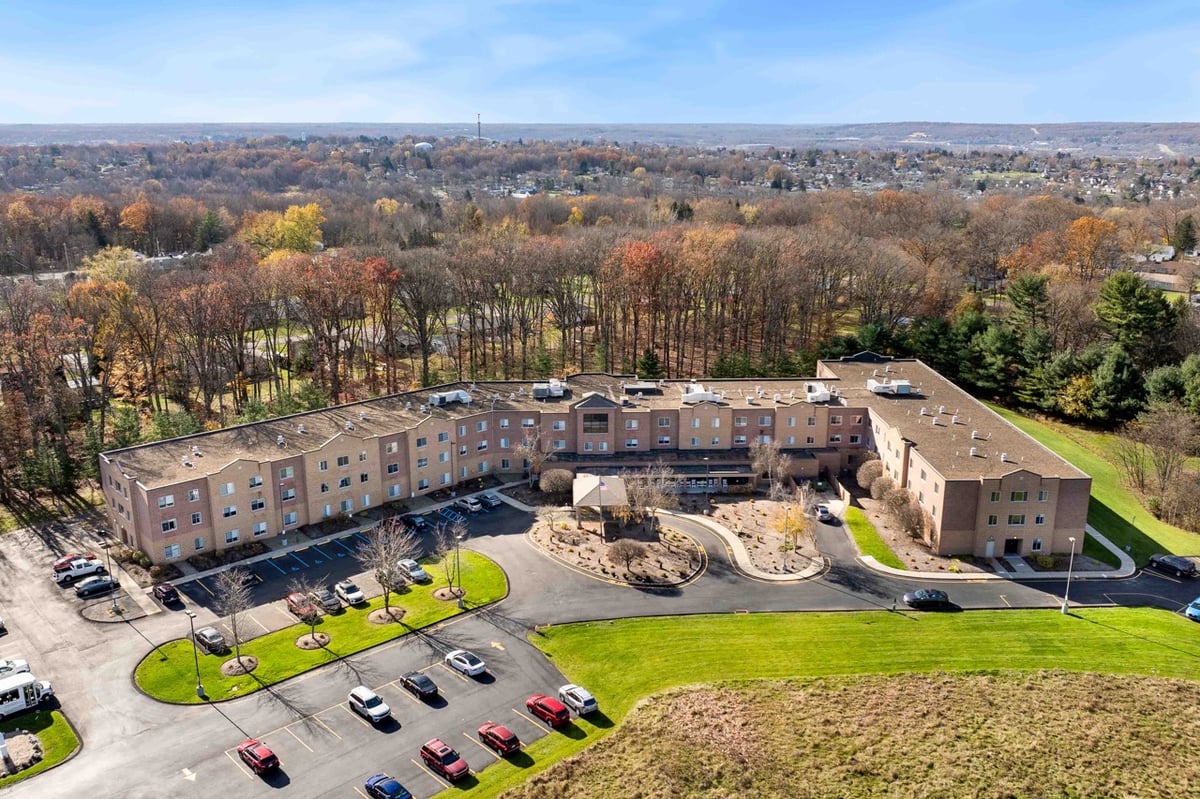
For older adults considering Whispering Oaks in Hermitage, PA, the first step is understanding what the house costs today, what community living includes, and how each asset can support the next chapter.
Treat Your House as a Financial Asset
Your house may provide more than equity. It may also produce monthly income, support a loan strategy, or remain part of your estate plan. The right approach depends on the property, local rental demand, taxes, insurance, and your long-term goals.
Using rental income to pay for senior living, in whole or in part, can be practical when the expected rent comfortably exceeds ongoing property expenses. A professional property manager may handle tenant communication, rent collection, maintenance coordination, and inspections, which can reduce the demands of being a landlord. However, a property manager also represents an additional cost.
Before renting, estimate net income rather than focusing only on the expected monthly rent. Consider landlord expenses such as:
- Property management fees and leasing costs.
- Taxes, insurance, and association fees.
- Repairs, seasonal upkeep, and emergency reserves.
- Possible vacancies and tenant turnover.
A financial or tax professional can also help explain how rental income may affect your tax situation.
Compare Community Costs & Current Household Spending
The question, “Can you afford senior living and keep your house?” is easier to answer when you compare complete monthly budgets. Be sure to track the full cost of homeownership, not just the mortgage. Additionally, remember that a community fee will likely replace some bills you already pay, such as for food, utilities, transportation, housekeeping, maintenance, and entertainment.
Whispering Oaks offers a newly renovated setting with three chef-prepared meals each day, housekeeping, apartment maintenance, scheduled transportation, and social programs. Residents also have access to spaces such as a theater, game room, library, Health & Fitness center, lounges, country store, and private dining room.
Include these categories in a side-by-side budget:
- Current mortgage or loan payment and community fee.
- Utilities, groceries, transportation, and household services.
- Property taxes, insurance, repairs, and landscaping.
- Social spending, memberships, and dining expenses.
This comparison can show whether keeping your home while in senior living is more manageable than it first appears.
Explore Financing Options for Independent Living with supportive services**
Several funding sources may work together. Social Security, pensions, retirement account withdrawals, investment income, and annuity payments can form a predictable monthly base. Some households also use savings for initial moving costs while preserving the property as a longer-term asset.
When comparing financing options for Independent Living with supportive services**, a home equity loan, home equity line of credit, or reverse mortgage may provide access to equity without an immediate sale. Each option has eligibility rules, fees, repayment terms, and risks. Review the details with qualified financial and legal professionals before using your house to fund community expenses.
The goal is not simply to cover the first year. Build a plan that remains sustainable if rental income changes, property expenses rise, or your priorities shift.
Keep Flexibility at Whispering Oaks
Our Independent Living with supportive services** community is designed to support your independence while offering access to additional help—only when and if you want it. A choice of third-party providers is available onsite for your convenience, but you are under no obligation to use any particular one. This flexible approach is perfect for individuals or couples with varied needs. Extend your independent lifestyle by choosing to make our community your home.
This model may help residents maintain autonomy while choosing optional third-party services only when desired. It can also make financing decisions easier to revisit over time, rather than forcing one permanent choice at move-in.
Frequently Asked Questions
Can You Afford Senior Living & Keep Your House?
Possibly. Add all income sources, estimate net rental or investment income, and compare them with both community costs and remaining property expenses.
Is Rental Income Enough to Cover Senior Community Costs?
It depends on the local rental market and the house’s expenses. Calculate net income after fees, taxes, insurance, repairs, and vacancies.
How Do You Afford Independent Living with supportive services** & Keep Your House?
Many households combine retirement income, investments, savings, rental proceeds, or home equity. A financial professional can help test the plan under several scenarios.
Plan Your Next Step
Keeping your house can preserve flexibility, but the numbers should support your lifestyle without creating unnecessary financial strain. Schedule a personalized tour of Whispering Oaks to explore apartment homes, included services, and community spaces in person.
A choice of third-party providers is available onsite for convenience, but residents are under no obligation to use any particular one.